Financial institutions now have to support more payment methods, markets, assets, and transaction models while keeping operational complexity under control. That makes payment architecture a strategic issue, not just a technical one. The challenge is to create an infrastructure that can evolve as payment behavior, regulation, and settlement models change.
What makes a payment stack future-proof?
A future-proof payment stack for financial institutions can add new payment rails, assets, markets, and regulatory controls without forcing the institution to rebuild its core architecture. Future-proofing doesn’t mean predicting which payment rail will win. It means building enough modularity to add or replace rails without rebuilding the core stack. Customer products, payment logic, compliance, settlement, and ledgering need clear interfaces, while the rails underneath them can change as business needs change.
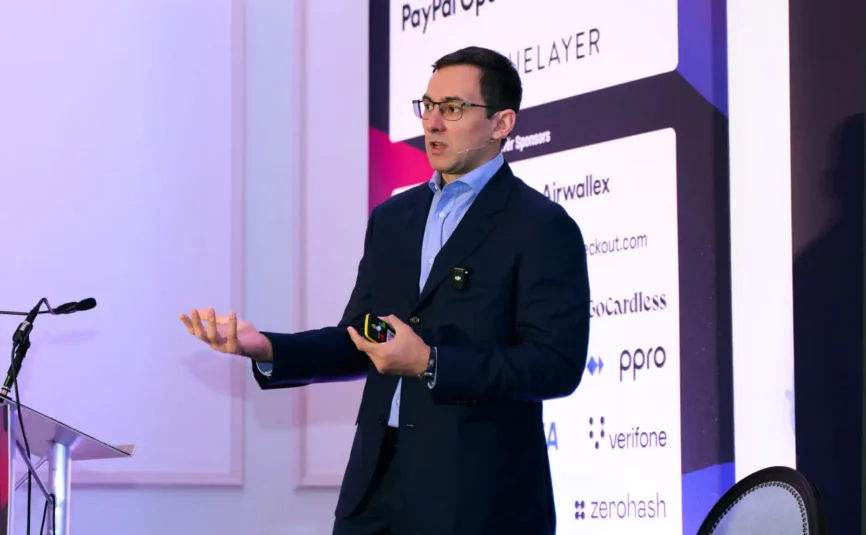
That principle matters because the next payment environment will be more programmable. At a Payments Leaders’ Summit, Pavel Kashuba, Strategic Leader at Coinspaid Solutions, put the challenge in operational terms:
Agentic commerce requires payment infrastructure with programmability, instant finality, and no humans in the loop. Most banking systems are not designed for this. Blockchain infrastructure is

The point for financial institutions is broader than blockchain itself. Their architecture needs to support transactions initiated and completed by software, with controls embedded directly into the flow.
The core layers of a future-proof payment stack
A modern payment infrastructure for financial institutions works best as a set of connected layers. Each layer has a defined responsibility, which makes individual components easier to replace or extend.
| Layer | Primary role |
|---|---|
| Customer and product | Banking apps, merchant products, wallets, and embedded finance |
| API and integration | Connects internal products, partners, and external systems |
| Payment orchestration | Selects rails, routes transactions, handles retries, and applies business rules |
| Payment rails | Cards, bank transfers, local instant rails, blockchain networks, and stablecoins |
| Digital asset infrastructure | Wallets, key management, blockchain connectivity, and transaction management |
| Liquidity and FX | Converts currencies and digital assets and supports treasury operations |
| Compliance and risk | KYC/KYB, AML, sanctions controls, transaction monitoring, and risk scoring |
| Settlement | Moves and finalizes funds or assets |
| Ledger and reconciliation | Records balances, matches transactions, and supports financial reporting |
| Data and monitoring | Provides operational visibility, analytics, alerts, and performance data |
An institution doesn’t need to build every layer itself. The architectural test is whether a new rail or provider can be connected without forcing changes across customer applications, compliance logic, treasury processes, and the general ledger. Tight coupling makes every expansion project larger. Modular interfaces keep the scope contained.
The future of payment infrastructure is multi-rail
A payment stack for banks or fintech companies has to handle different transaction types through different rails. Domestic instant payments may use a local bank network. Card purchases still belong on card networks. A digital asset transfer requires blockchain infrastructure. Some cross-border B2B flows may use bank rails, while others may use stablecoins when the commercial and regulatory case supports them.
This makes rail selection a routing problem. The stack should evaluate destination, currency, cost, settlement time, liquidity, compliance requirements, counterparty support, and operating hours. A rail-agnostic architecture gives the institution room to change that decision as markets and infrastructure develop.
APIs and payment orchestration belong at the center
Monolithic payment systems make expansion expensive because business logic, integrations, and settlement processes become tied to a specific rail. APIs separate capabilities from the systems that consume them.
Payment orchestration then turns those capabilities into transaction logic. It can decide which route to use, apply limits, check provider availability, trigger compliance controls, manage retries, and return a consistent transaction status to the product layer. This is especially important for institutions operating across several markets, where the optimal route can differ by currency, customer, and transaction type.
Where blockchain and stablecoins fit
Blockchain should be treated as one financial rail within the broader payment infrastructure architecture. Stablecoins are one use case of that rail, alongside other digital assets, tokenized deposits, and blockchain-based settlement models.
The scale of stablecoin activity shows why institutions are evaluating this layer. According to Artemis Analytics data cited by Bloomberg, stablecoin transaction volume reached $33 trillion in 2025, up 72% year over year. That number needs context. Raw on-chain volume includes trading, exchange operations, bridge activity, and automated transactions, so it isn’t equivalent to consumer or business payment volume. Visa’s Onchain Analytics Dashboard separates adjusted and unadjusted activity and filters categories such as bots, bridges, and internal exchange operations. For infrastructure planning, the useful signal is the growth of an additional settlement rail, not a headline comparison with card networks.
Cross-border payments remain a practical stress test
Global payments expose weaknesses that domestic systems can hide. A single transfer may pass through correspondent banks, FX providers, different operating windows, reconciliation processes, and several regulatory environments. The resulting cost and settlement time vary significantly by corridor.
Kashuba’s Summit observations highlighted West Africa, Southeast Asia, and South Asia as markets where correspondent banking can remain expensive and slow. A blockchain rail can be useful where it removes a meaningful operational constraint, such as limited settlement hours, a long intermediary chain, or difficult multi-currency treasury flows. It still needs adequate liquidity, compliant counterparties, reliable on-ramps and off-ramps, and a clear regulatory basis. Adding blockchain without solving a corridor-specific problem only adds another integration.
Compliance has to sit inside the transaction flow
New rails don’t remove existing responsibilities. A future-proof payment stack needs compliance controls that can operate consistently across cards, bank transfers, and digital assets.
That means transaction flows should expose the data required for KYC/KYB, AML, sanctions screening, transaction monitoring, case management, and audit records. The control framework also needs to account for jurisdiction and asset type.
Regulatory maturity differs by market. In the EU, MiCA provisions for asset-referenced tokens and e-money tokens applied from June 30, 2024, while the broader framework applied from December 30, 2024. In the U.S., the GENIUS Act was signed into law in July 2025. Implementation is still proceeding through rulemaking, with January 18, 2027 currently identified as the expected effective date. The U.K. established a new cryptoasset regulatory regime in 2026, scheduled to come into force in October 2027, while the government continued separate work on stablecoin payment services. Architecture therefore needs configurable controls instead of a single global policy.
Agentic commerce adds another infrastructure requirement
Agentic commerce changes who initiates a payment. Software may select a supplier, negotiate within preset parameters, and trigger a transaction without a person approving each step.
That model requires more than an API endpoint. The payment stack needs machine-readable permissions, programmable limits, real-time risk checks, predictable transaction status, and settlement that can operate continuously. Identity and authorization become critical because the institution has to distinguish what an AI agent is allowed to do from what its owner is allowed to do.
Kashuba’s Summit point is useful here because it frames programmability as an infrastructure issue. Institutions that keep payment approval dependent on manual back-office steps will struggle to support machine-to-machine commerce at scale.
Build vs integrate: what should financial institutions own?
Internal ownership makes sense where technology creates competitive differentiation or where regulation, security policy, or operating scale requires direct control. Customer relationships, proprietary data, governance, product rules, and institutional risk policy usually sit close to that boundary.
Functions that demand continuous protocol maintenance can often sit outside the institution, including network access, wallet services, transaction handling, and operational monitoring. These areas require specialist engineering but may contribute little visible differentiation to the customer proposition. A hybrid model lets the institution keep authority over strategic controls while integrating infrastructure where specialist scale matters.
The practical decision can be reduced to 5 questions:
- Does owning this capability create a durable commercial advantage?
- Does regulation or internal policy require direct control?
- Can the institution operate and secure it continuously over several years?
- What is the full cost of ownership, including upgrades, monitoring, incident response, and specialist staff?
- How quickly does the business need to launch, and what is the opportunity cost of waiting for an internal build?
What to look for in an infrastructure provider
Provider selection should start with architecture and operating risk, not the length of the feature list. Financial institutions should examine API quality, modularity, supported rails, blockchain expertise, stablecoin capabilities, liquidity, settlement models, compliance tooling, scalability, uptime commitments, security, reporting, reconciliation, geographic coverage, implementation time, and operating history.
Portability deserves equal attention. The institution should understand who controls private keys, how transaction signing works, where data sits, what happens during a provider outage, and how difficult it would be to migrate.
Coinspaid is one example of a provider that supports a modular approach to digital asset infrastructure. Its infrastructure model allows institutions to retain control over keys, assets, and transaction signing while using external systems for blockchain operations and transaction management. That structure illustrates the broader design principle: external infrastructure can reduce engineering load without requiring a financial institution to give up every layer of control.
FAQ
A modular architecture where change stays localized instead of forcing a core rebuild.
Think in 4 groups: product access, transaction routing, control and settlement, and financial records and monitoring.
Only when it solves a defined settlement, asset, corridor, or programmability need.
Inside the blockchain and digital-asset layer, as one settlement instrument among several, with liquidity and compliance dependencies.
Start with machine-readable authority, automated checks, predictable transaction status, and audit-ready records.